
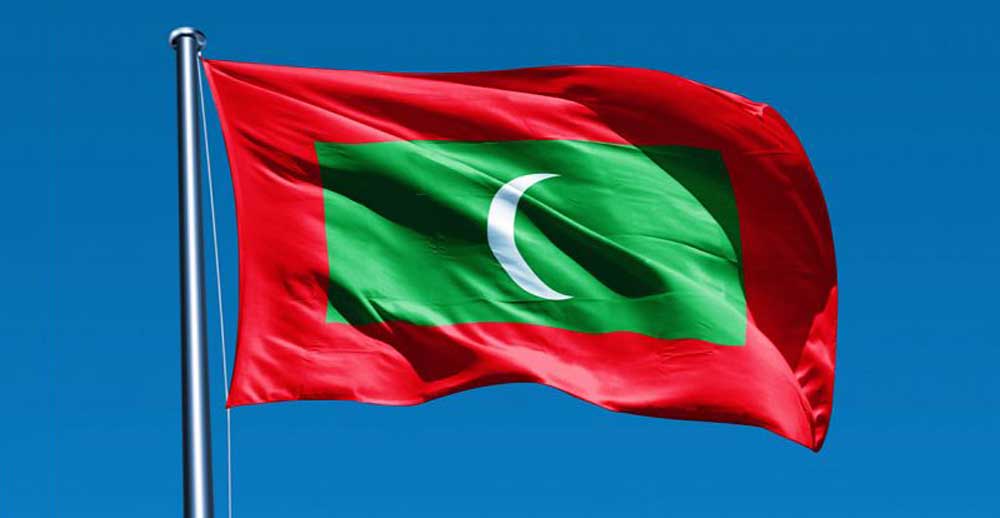
Kathmandu. The Maldives has tightened the rules related to foreign investment in various sectors.
According to the amended provision, at least 25 percent local ownership is mandatory for foreign investment in certain sectors related to construction, real estate, auditing and information technology. Some businesses are reserved only for Maldivian citizens.
According to Mohamed Saeed, Minister of Economic Development, Transport and Trade, Maldivian citizens must have at least a 25 percent stake in foreign investment in construction projects worth less than $15 million and real estate projects worth less than $100 million. The same rule applies to auditing and information technology services.
Similarly, residential real estate projects worth less than $100 million and some activities in general maritime transport services have been reserved only for Maldivian citizens.
The new provision, which came into effect in 2024, will cover about 150 businesses with foreign investment, Saeed said.
According to him, 29 foreign investment businesses operating in the areas reserved only for local people have been closed while 17 foreign investors have applied to meet the new requirements.
The new policy also covers wholesale and retail trade, logistics services and passengers and cargo sales agencies of airlines operating in the Maldives. Minister Saeed said that 17 businesses involved in wholesale and retail trade have shown interest in involving local shareholders.
Foreign investors working in areas where the new rules are implemented will be given time to restructure their businesses or exit related activities. In some areas, opportunities for joint investments and partnerships with Maldivian partners will continue.
According to the Ministry of Finance, the purpose of the new arrangement is to expand opportunities for local businesses and to continue foreign investment in areas where international expertise can contribute to economic development.





प्रतिक्रिया दिनुहोस्