

Kathmandu. The Independent Power Producers’ Association, Nepal (IPPAN) has demanded a review of the draft ‘Directive on General Qualification for Public Issue, 2083’ proposed by the Securities Board of Nepal (SEBON) keeping in view the nature and capital requirement of the hydropower sector.
Saying the proposed provision could affect capital management, public release process and continuity of investment, IPPAN suggested removing and amending various provisions in the proposed draft.
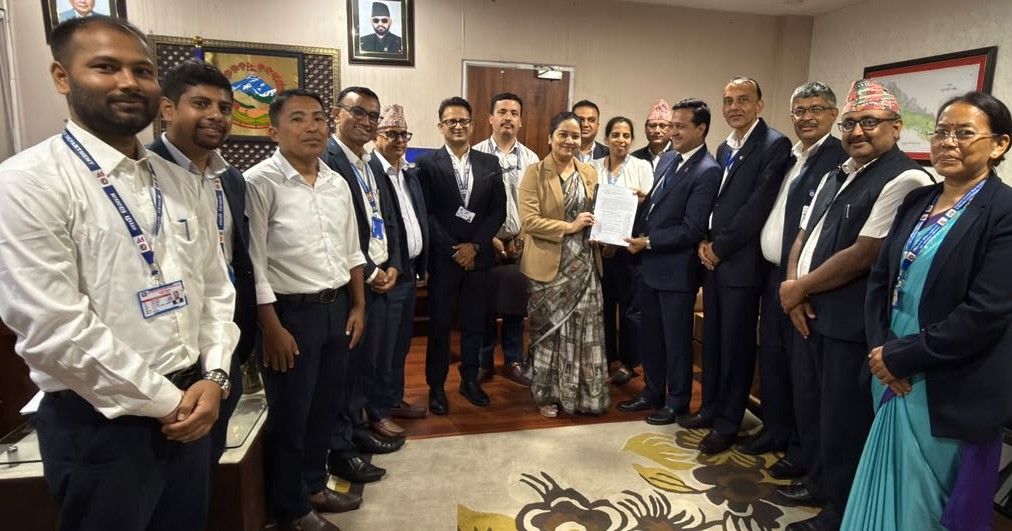
IPPAN has also submitted a suggestion regarding the proposal of the directive in Sebon on Tuesday. IPPAN President Mohan Dangi said that since the energy sector is directly related to economic development, industrialization, employment generation, revenue mobilization and foreign exchange earnings, the condition should not be put in place to stop the investment by looking at hydropower projects as a long-term and large-scale capital required sector. According to him, the nature of the project and capital requirement should also be taken into consideration along with the protection of investors while making the provision related to public issue.
“The hydropower sector needs a different regulatory system than other sectors,” he said, adding that it would not be appropriate to apply the same standard to all institutions as the business nature and capital structure of banking, insurance, hydropower, pharmaceuticals and manufacturing industries are different. He suggested that a separate chapter and a separate IPO checklist should be made in the case of the hydropower sector.
Demand to remove the provision of stopping IPO for projects that are not in operation
IPPAN has argued that the draft issued by SEBON has proposed that the hydropower company should be continuously engaged in business before issuing ordinary shares, but this provision should be removed as it would be impractical for hydropower projects.
IPPAN claims that the projects promoted by the hydropower companies are considered to be operational only after the completion of the construction and the production of electricity is considered to be operating.
IPPAN Chair Dangi said that since a huge capital would be required in the construction phase of hydropower projects, an arrangement was necessary to mobilize public investment in this phase.
IPPAN has suggested that a provision should be made to apply for the IPO after the physical progress of the hydropower project is about 65 percent. IPPAN has suggested to SEBON that a separate IPO checklist should be prepared according to the nature of the project for hydropower.
IPO issue should be allowed even if the net worth is less than the face value
IPPAN has demanded that the provision regarding net worth per share of the corporate body should not be less than the face value in the draft of SEBON, and this provision should be removed for manufacturing industries, especially hydropower projects. “Due to depreciation during the construction of the hydropower project, the net worth of the company may come down to less than Rs 90. However, the IPO should not be stopped only on the basis of the net worth of the construction period as the income situation will be different after the completion of the project and the production of electricity,” said Dangi.
IPPAN has suggested that the investors should be informed about the risks on the basis of full disclosure, underwriting and credit rating and the way should be opened for the general public to issue shares. IPPAN claims that if the proposed provision on net worth remains in place, about 60 per cent of hydropower projects may not be able to issue shares to the public. IPPAN has also suggested to SEBON to make a provision to allow IPO issuance if the net worth is up to Rs 90 based on the ‘power value’ of the hydropower company.
Sebon should not set debt-to-capital ratio
In the draft of the directive, it has been proposed that SEBON can set the criteria related to loan-capital ratio, interest repayment capacity and other financial indicators according to the regional nature, but the provision related to debt-capital ratio should be removed.
According to IPPAN, the issue of how much loan to take and how much self-capital a hydropower project should be kept is related to the financial management of the project, and if the approval of SEBON is made at the time of IPO issuance, then another level of regulatory approval will be added before the financial management of the project.
IPPAN argues that after the agreement with the bank regarding the financial management of the project, during the IPO issuance, SEBON should not stop the process by looking at the debt-capital ratio. It says that such a provision can also cause problems in the management of the long-term self-capital ratio.
Thousands of founding shareholders ‘fit and proper’ test impossible
}
According to IPPAN, the draft directive has proposed that the promoter shareholders, directors and chief executive officers of the company should undergo ‘fit and proper’ test from SEBON and the promoter shareholders should not be included in it.
“There can be thousands of promoter shareholders in a hydropower project. It may not be practically possible to conduct a fit and proper test and declaration of each promoter shareholder. Therefore, such a system should be limited to the directors and management,” said the suggestion letter submitted by IPPAN to SEBON.
Similarly, IPPAN has said that it would not be justified to stop the IPO of a company in such a way that thousands of other investors will be affected because one of the founding shareholders is blacklisted or involved in financial crimes. IPPAN also demanded that the draft should clarify who is targeted by the provision that the blacklist has not been released within a certain period of time.
Similarly, it has been proposed that the provision proposed in the draft can set additional conditions for the board while approving a public issue if it deems it necessary for investor protection, market stability, sound financial system and public interest. IPPAN argues that such a provision would give the employees of Sebon unlimited discretion powers and would increase the possibility of irregularities.
Similarly, in the draft directive, a provision has been proposed to conduct an independent legal examination of the agreements between the contractor and the promoter company, but IPPAN has also demanded that it be removed. IPPAN argues that the provision of the board to conduct a legal examination or forensic audit by submitting the private business agreements between the contractor and the promoter to Sebon is beyond its jurisdiction.
It has also suggested that separate rules regarding the independent opinion of assessors, technical experts, environmental experts or other concerned persons should be removed. IPPAN has said that if the due diligence provision regarding the technical and cost of the project is elsewhere, then additional parties will not be required for the same work. It also said that environmental issues do not fall under the jurisdiction of SEBON.
Request to timeline IPO approval process
IPPAN has demanded that SEBON should set a clear timeline for the initial examination and detailed evaluation to be carried out. The draft directive provides for seeking more details after examining the completeness, documents, fees and minimum legal qualifications of the application, but it has not proposed a definite time frame for the same, saying IPPAN has not proposed a time-bound process for the same.
IPPAN has suggested that the preliminary test should be completed within 15 days from the date of receipt of the application and if additional documents are sought, the test should be completed within 7 days of receipt of the document. It has also suggested that a provision should be made to complete the detailed evaluation within 45 days and make a mandatory decision within a maximum of 60 to 90 days. By keeping such a time limit, the tendency of public companies to hold files for a long time after submitting the required documents will be controlled, IPPAN said.
IPPAN has demanded that the draft directive also consider environmental risk as a basis during the evaluation of the application for the issuance of shares of a hydropower company. IPPAN argues that there is no need to include the issue of environmental risk in the SEBON guidelines as it is the concerned body for environmental study and regulation.
IPPAN has also suggested that the proposed provisions of SEBON, such as additional information, expert opinion, on-site inspection, special audit or re-due diligence should be framed with clear criteria if deemed necessary. IPPAN said that the vague wording of ‘if deemed necessary’ could lead to variations in regulatory decisions, so it should be clarified in what circumstances such powers will be exercised.
The grounds for rejecting the application should be clear
The draft guidelines have proposed a provision to deny IPO approval if there is a concealment of important facts, false or misleading information, not meeting the minimum qualifications, serious weaknesses in corporate governance or adversely affecting the interest of public investors, IPPAN has specifically asked for further clarification saying that the wording “financial condition is contrary to the interest of public investment” and “situation adversely affecting the interest of ordinary investors”. It said that the grounds for regulatory decisions should be measurable and clear.
Old rules for hydropower projects in pipelines
}
IPPAN has demanded that the new guidelines should not affect the hydropower companies that have already filed applications for the IPO due to the new norms. IPPAN has also suggested that the hydropower companies which have already applied for the IPO should be allowed as per the old rules as per the earlier ‘Guidelines on General Qualification for Public Issue, 2074’.
It demands that companies should be given adequate transitional time even after the new directive comes into force. IPPAN has said that the new system on public issue should be made in such a way that it is easy for real sector companies to mobilize capital along with investor protection, good governance and transparency. IPPAN believes that the regulatory reforms will affect the cycle of project construction and capital mobilization as the long-term capital requirement in the hydropower sector is high.





प्रतिक्रिया दिनुहोस्